Turning 65 comes with deadlines, and missing one can follow you for years. This checklist walks you through the dates, the paperwork, the questions worth asking and the penalties worth avoiding. Print it, fill it in, and bring it to your free consultation.
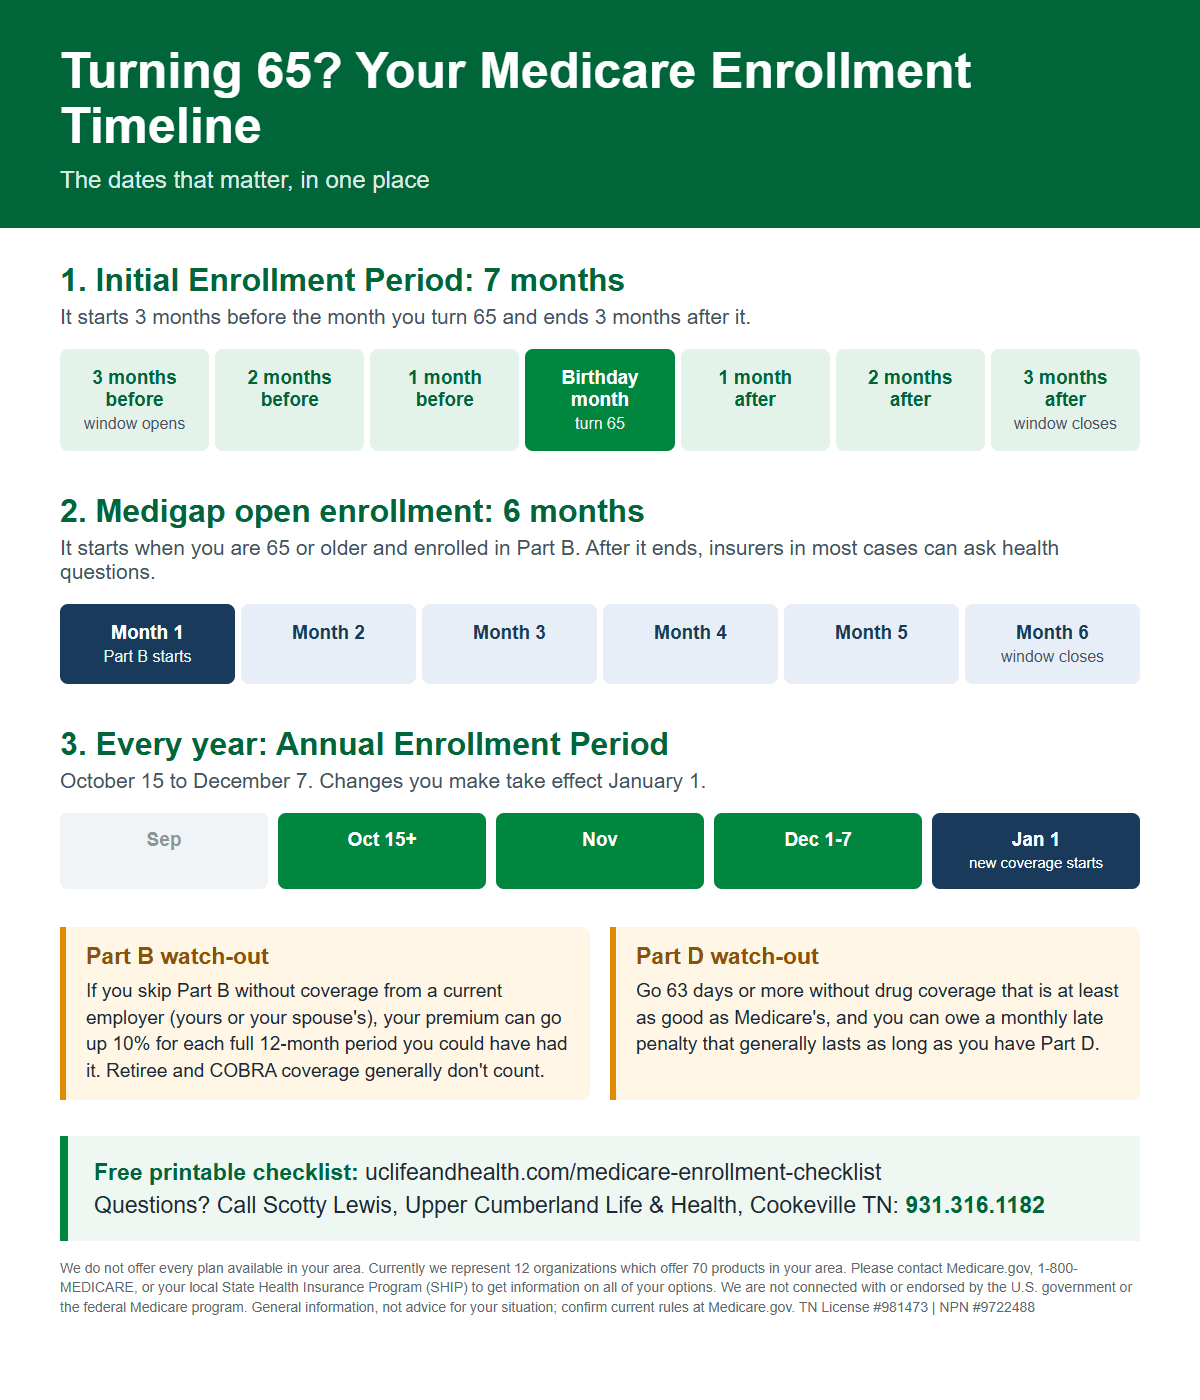
1. Know your dates
- My 65th birthday: ____________ (my Medicare month)
- My Initial Enrollment Period is a 7-month window: the 3 months before the month I turn 65, the month I turn 65, and the 3 months after. Window opens: ____________ Window closes: ____________
- If I already receive Social Security or Railroad Retirement benefits, I'm generally enrolled in Parts A and B automatically. I watch the mail for my Medicare card.
- If I'm still working and have employer coverage, I ask HR whether it counts as creditable coverage and how it works with Medicare before I decide what to do about Part B.
- Every year, the Annual Enrollment Period runs October 15 to December 7. Changes take effect January 1.
2. Understand the pieces
- Part A: hospital coverage.
- Part B: doctor visits and outpatient care.
- Part C (Medicare Advantage): a plan from a private company that bundles Parts A and B and often Part D.
- Part D: prescription drug coverage from a private company.
- Medicare Supplement (Medigap): optional coverage from a private company that helps with costs Original Medicare leaves.
3. Gather before I compare
- My Medicare number or Social Security number, and photo ID.
- A list of my doctors, hospitals and specialists.
- A list of my prescriptions with dosage and how often I take them.
- My preferred pharmacy.
- Details of any coverage I have now: employer, spouse, retiree, or marketplace.
4. Questions to ask about any plan
- Are my doctors and hospitals in the plan's network?
- Are my prescriptions covered, and at what cost tier?
- What is the plan's yearly out-of-pocket maximum?
- Do I need referrals to see specialists?
- What happens if I travel, or spend part of the year in another state?
5. Avoid the penalties
- Part B: I can sign up when I turn 65, but I don't have to if I or my spouse have coverage through a current employer. If I skip Part B without that kind of coverage, my premium can go up 10% for each full 12-month period I could have had it, and the penalty generally lasts as long as I have Part B. If I'm covered through current work, I can usually enroll later without a penalty, but retiree or COBRA coverage generally doesn't count. I confirm the details with HR before I decide.
- Part D: if I go 63 days or more without drug coverage that is at least as good as Medicare's, I can owe a monthly late penalty that generally lasts as long as I have Part D.
- Medigap: I get a 6-month open enrollment period that starts when I'm 65 or older and enrolled in Part B. After it ends, insurers in most cases can ask health questions.
6. Get free help
- Medicare.gov or 1-800-MEDICARE.
- My local State Health Insurance Program (SHIP), which offers free counseling in Tennessee.
- A licensed local agent, such as us, to walk through the plans we represent. A consultation is free and there is no obligation to buy anything.
Download the printable checklist (PDF)
Want help filling it in? Book a free consultation or call 931.316.1182. Prefer a monthly email with Medicare and retirement tips? Sign up for our newsletter.
We do not offer every plan available in your area. Currently we represent 12 organizations which offer 70 products in your area. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Program (SHIP) to get information on all of your options. We are not connected with or endorsed by the U.S. government or the federal Medicare program.