Medicare is complicated, and the rules change every year. We’re an independent insurance agency serving all 95 Tennessee counties from our Cookeville office. We help you compare available plans in your ZIP code at no cost. Turning 65 or switching plans? Helping a parent sort out what they have? We walk through your options in plain language and find what fits your budget and health needs. Turning 65? Start with our free Medicare enrollment checklist.
Your Four Medicare Options Explained
Medicare isn’t a single plan. It’s a system with four interrelated parts. Here’s what each one does and how they fit together.
Part A — Hospital Coverage
Part A covers inpatient hospital stays, skilled nursing facility care, hospice, and some home health services. Most people don’t pay a monthly premium for Part A if they’ve worked at least 40 quarters and paid Medicare taxes. The Part A deductible in 2026 is $1,736 per benefit period. That’s per hospital stay, not per year, so a second hospitalization can trigger another deductible.
Part B — Medical Coverage
Part B covers doctor visits, outpatient care, preventive services, and durable medical equipment. The standard monthly premium in 2026 is $202.90. Higher-income enrollees pay more through an IRMAA (Income-Related Monthly Adjustment Amount) surcharge tied to their income from two years prior. When you’re timing your Medicare enrollment alongside a Social Security claim, that income figure matters. We can walk you through it.
Part C — Medicare Advantage Plans
Medicare Advantage is an alternative to Original Medicare offered by private insurers approved by Medicare. Plans come in two structures. HMO plans limit coverage to in-network providers, except for emergencies. PPO plans allow out-of-network care at a higher cost, so you have more flexibility in choosing providers. Both bundle Part A and Part B coverage. Most add prescription drug coverage along with dental, vision, and hearing benefits. Many plans are available at $0 monthly premium.
The network choice matters more than most people realize. In rural Upper Cumberland counties, some HMO networks are thin — your current doctors may not be covered. Before recommending any Advantage plan, we check network adequacy for your specific ZIP code and confirm your providers are in.
Part D — Prescription Drug Plans
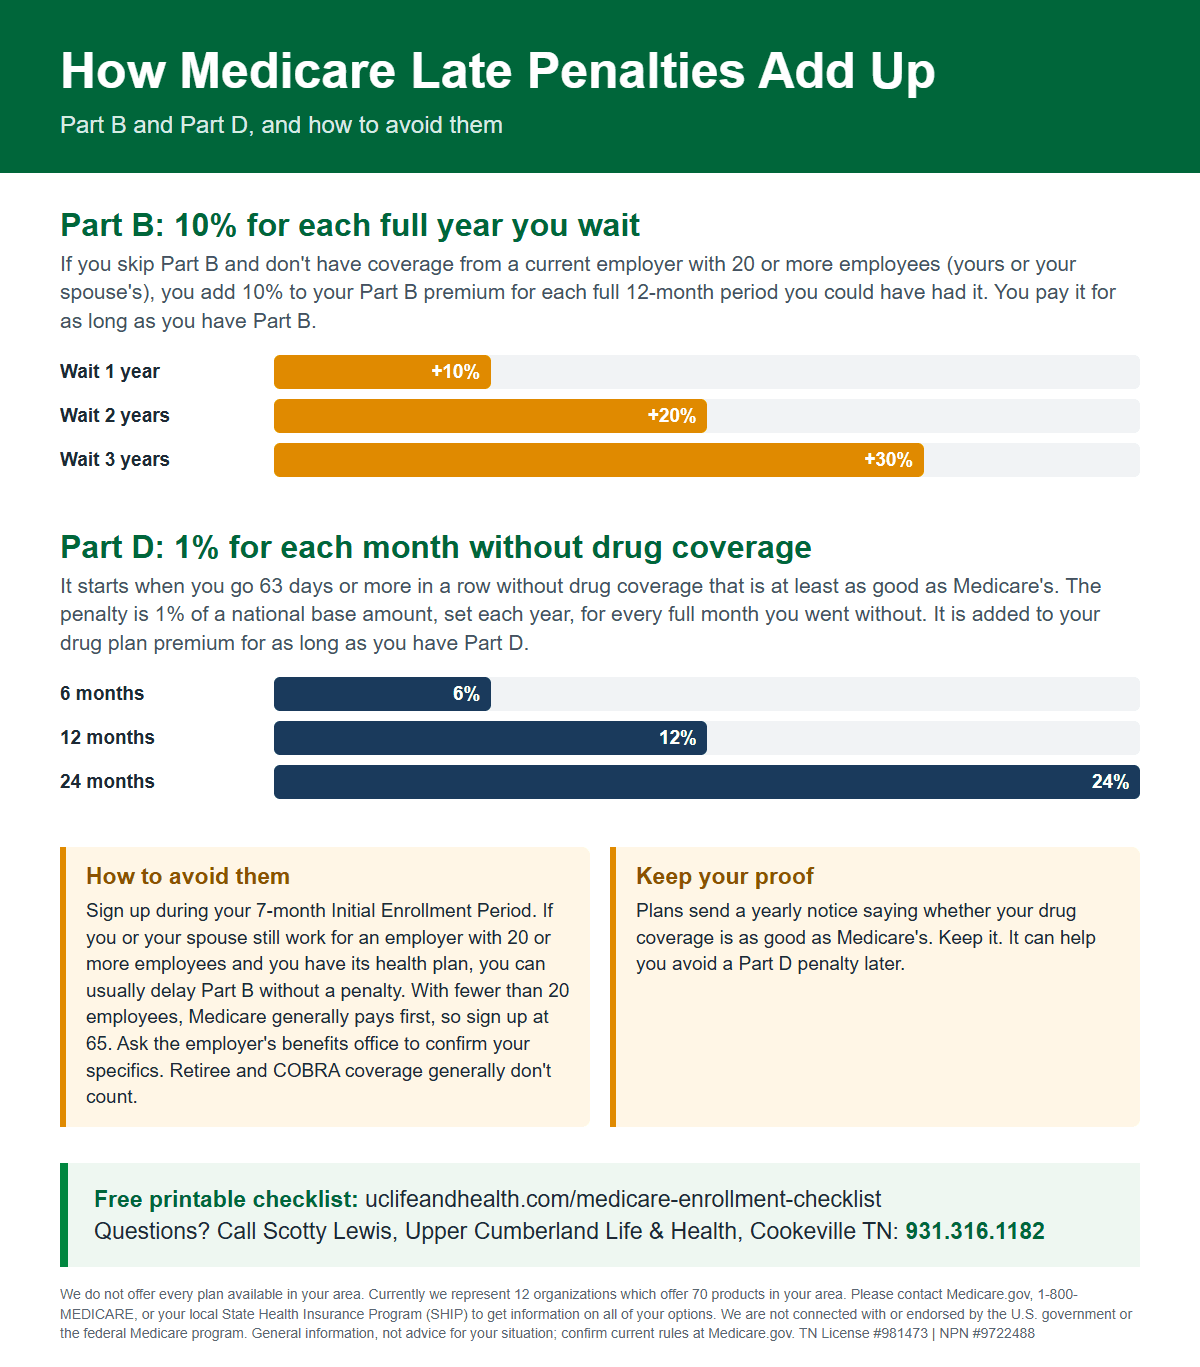
Part D is a standalone drug plan that works alongside Original Medicare or a Medicare Supplement. Coverage varies by plan formulary, so the same drug can be covered at different tiers by two different Part D plans. Enrollment timing matters. Skip Part D when you’re first eligible, and you’ll owe a late enrollment penalty. It’s 1% of the national base premium for every month you went without creditable coverage. That penalty is permanent. We compare formularies across available Part D plans to find the best fit for your prescriptions.
Get a Free Medicare ConsultationMedicare Supplement (Medigap) Plans in Tennessee
Original Medicare has gaps. Parts A and B together leave you responsible for deductibles, copayments, and coinsurance. A Medicare Supplement plan, commonly called Medigap, fills those gaps.
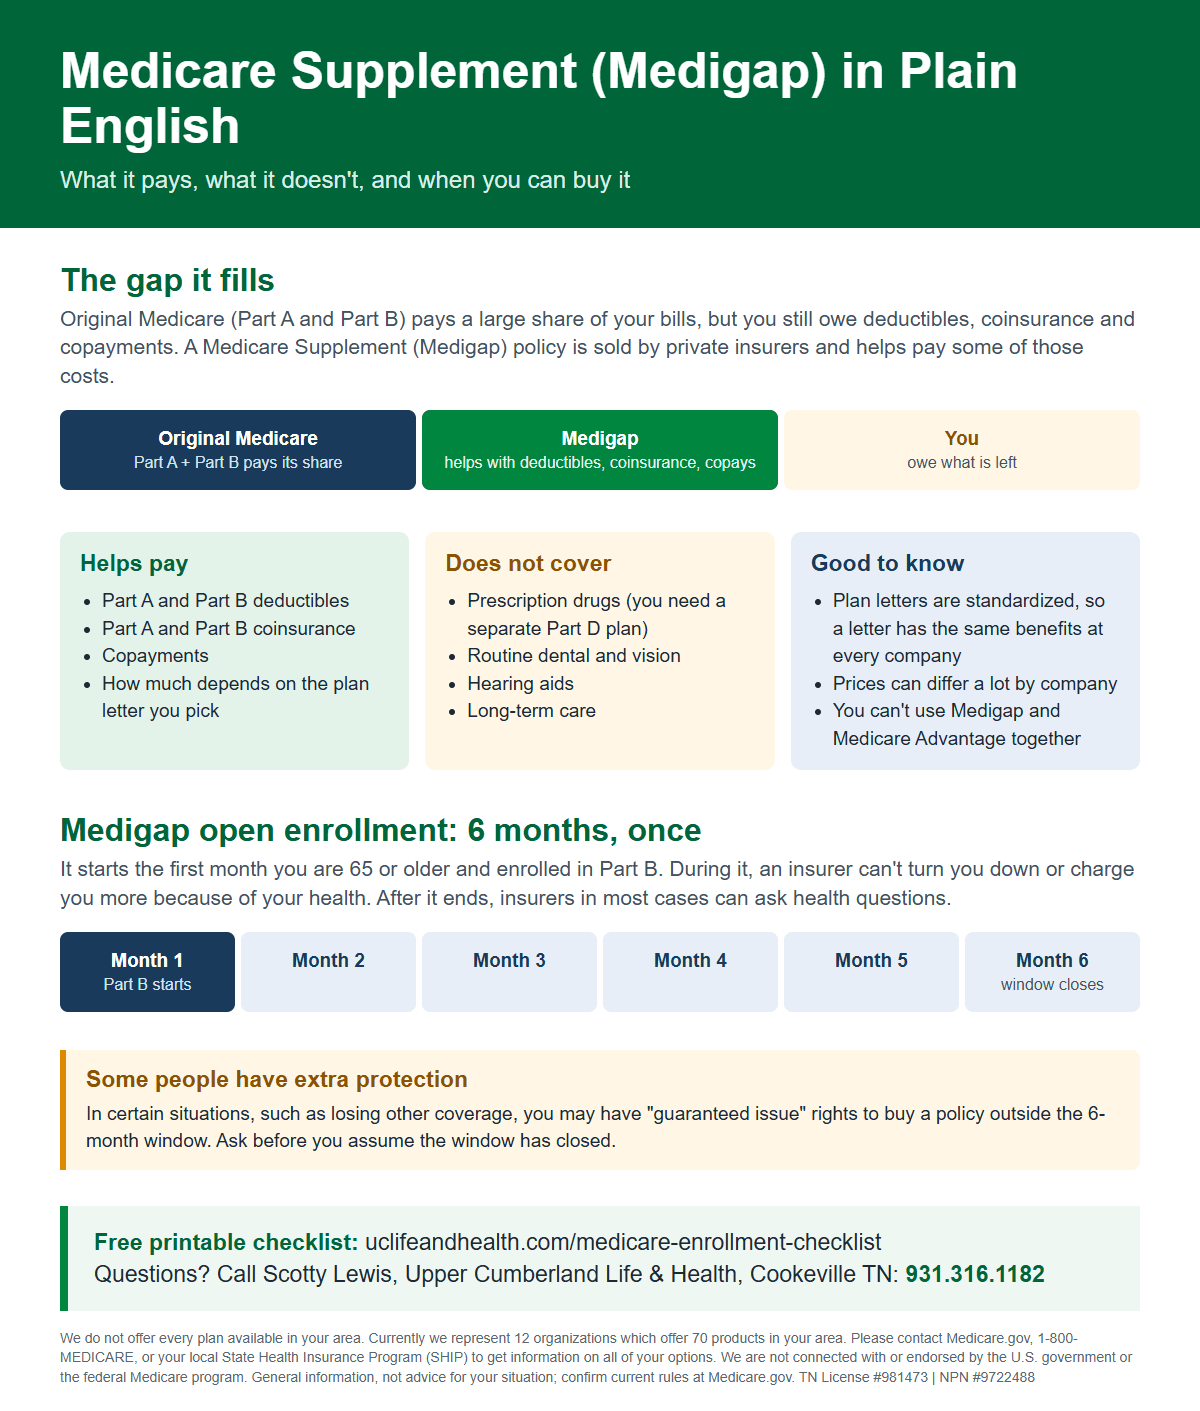
Medigap plans are sold by private insurers but standardized by federal law. Every Plan G from every carrier covers the same benefits. The only variable is the monthly premium. That’s why comparing carriers before you enroll is worth your time.
Plan G and Plan N are the two plans most new enrollees consider. Plan G covers everything except the Part B deductible ($283 in 2026). Plan N has a lower monthly premium. It adds copayments of up to $20 for doctor visits. ER visits that don’t lead to a hospital stay cost up to $50.
Which one fits depends on how often you use medical services and whether the premium savings outweigh the potential copayment exposure. We’ll run the numbers for your situation.
One thing most agents skip: the same Plan G from different carriers can vary by $80 or more per month for the same enrollee. That variation is legal, common, and avoidable if you compare before you enroll. We shop every Medigap carrier licensed in Tennessee.
Call 931-316-1182 for a free side-by-side comparison. No obligation.
Medicare Advantage
Vs. Medicare Supplement
Which Is Right for You?
This is the question we hear most. There’s no universal answer, but the comparison below shows how they differ on the factors that matter.
| Medicare Advantage | Medicare Supplement | |
|---|---|---|
| Monthly premium | Often $0 — copays apply when you use care | Higher monthly cost — most out-of-pocket gaps are covered |
| Drug coverage | Usually included | Requires a separate Part D plan |
| Provider access | In-network only (HMO) or preferred network (PPO) | Any doctor or hospital that accepts Medicare, anywhere in the U.S. |
| Dental, vision, hearing | Often included | Not included — add through ancillary plans |
| Out-of-pocket exposure | Annual maximum required by law — can reach thousands | Minimal with Plan G — predictable regardless of how much care you use |
| Works best for | Good health, low healthcare use, comfortable with network limits | Regular care needs, serious conditions, travel, or anyone who wants no surprises |
Advantage plans suit people in good health who want low monthly costs and are comfortable with a provider network. Supplement plans suit people with regular health needs. They give you predictable out-of-pocket costs and the freedom to see any Medicare-accepting provider anywhere in the country.
Call us and we’ll compare both options for your ZIP code, your doctors, and your prescriptions.
When Can You Enroll in Medicare in Tennessee?
Your first window is the Initial Enrollment Period. It lasts 7 months: it starts 3 months before the month you turn 65, includes your birthday month, and ends 3 months after. Enroll in the first 3 months and coverage starts the first day of your birthday month. Wait until your birthday month itself and there’s a one-month delay. Still working when you turn 65? If you or your spouse work for an employer with 20 or more employees, and you’re on that employer’s health plan, you can usually delay Part B. You sign up later during a Special Enrollment Period. It gives you 8 months after the job or coverage ends to enroll without a late penalty. With fewer than 20 employees, Medicare generally pays first, so sign up when you turn 65. Ask the employer’s benefits office to confirm your specifics. Source: Medicare.gov.
The Annual Enrollment Period runs October 15 through December 7 each year. Current Medicare enrollees use this window to switch plans or add or drop Part D. They can also move between Original Medicare and a Medicare Advantage plan. New coverage takes effect January 1.
Missing your Initial Enrollment Period without qualifying employer coverage creates a gap and a permanent penalty. We can tell you exactly where you stand before you make any move.
Why Work With an Independent Medicare Agent in Tennessee?
An independent agent represents multiple carriers, not one. A captive agent sells one carrier’s plans and fits you into their lineup. We compare plans from every carrier available in your Tennessee ZIP code and show you the options side by side. Your plan premium is set by the carrier, not the agent, so there’s no extra cost to using us.
Scotty Lewis is a Registered Social Security Analyst (RSSA), one of a small number of agents in Tennessee holding that credential. It matters here because Medicare and Social Security planning are connected. The age you claim Social Security affects your Medicare Part B premium through IRMAA. Getting both decisions right at the same time changes the numbers for most households. No local competitor offers this combination under one roof.
Scotty also holds the CSA (Certified Senior Advisor) designation, which reflects specialized training in the financial, health, and social issues affecting older adults.
We meet clients in person in Cookeville and the Upper Cumberland. For any of Tennessee’s 95 counties, we’re available by phone or Zoom. No cost, no obligation.
Frequently Asked Questions
Medicare Plans in Tennessee
Is it free to use a Medicare insurance agent in Tennessee?
Yes. Medicare agents are compensated by the carriers, not by you. Your plan premium is the same whether you enroll through us or go directly to the insurer. You get an independent comparison at no cost.
What’s the difference between Medicare Supplement and Medicare Advantage?
Medicare Supplement (Medigap) works alongside Original Medicare and covers gaps like deductibles and coinsurance. Medicare Advantage replaces Original Medicare with a private plan that bundles Parts A, B, and usually D. Supplement plans have higher monthly premiums but no network restrictions. Advantage plans often have lower or $0 premiums but limit you to in-network providers. You can’t use both: a Medigap policy doesn’t work with a Medicare Advantage plan, so you choose one path. Either way, you keep Part A and Part B and keep paying your Part B premium. Advantage plans cap your yearly out-of-pocket costs, and Supplement plans keep them predictable whether you use a little care or a lot. Which fits depends on how often you use care and how much cost certainty you want. We compare both for your ZIP code. Source: Medicare.gov.
Which Medicare Advantage plan is right for me in Tennessee?
There’s no single answer. The right plan depends on which carriers operate in your ZIP code and whether your doctors are in-network. It also depends on how your prescriptions are covered and what you can afford out of pocket. We compare the available plans in your area before you decide.
When is the Medicare Annual Enrollment Period in Tennessee?
October 15 through December 7 each year. Coverage changes take effect January 1. This is when you can switch plans, add or drop Part D, or move between Original Medicare and Medicare Advantage.
Can I change my Medicare plan at any time?
Generally, no. Changes are limited to designated enrollment periods. Exceptions include Special Enrollment Periods. Specific events trigger them: losing employer coverage, moving out of a plan’s service area, or your carrier leaving the market. If you’re not sure whether a window is open for you, call us and we’ll check.
Does Upper Cumberland Life & Health serve all of Tennessee?
Yes. Our office is in Cookeville. We meet clients in person across the Upper Cumberland and serve all 95 Tennessee counties by phone or Zoom. Call 931-316-1182 or use the form below to get started.
Serving All 95 Tennessee Counties From Cookeville
Our office is in Cookeville, in the heart of the Upper Cumberland. We meet clients in person in Cookeville, Crossville, Sparta, Livingston, Jamestown, and surrounding communities. We work with clients across the rest of Tennessee by phone and Zoom at no extra cost. That includes Nashville, Knoxville, Memphis, Chattanooga, and Jackson. We’ve helped clients across Putnam, White, Cumberland, Overton, Fentress, Jackson, Smith, and DeKalb counties and beyond. Distance isn’t a barrier.
Scotty Lewis compares Medicare plans from multiple carriers, with no carrier ties and no upsell pressure. He holds the Certified Senior Advisor (CSA) and Registered Social Security Analyst (RSSA) credentials.
Call 931-316-1182 for a free consultation, or use the button below. No cost, no obligation.
Get a Free Medicare Consultation